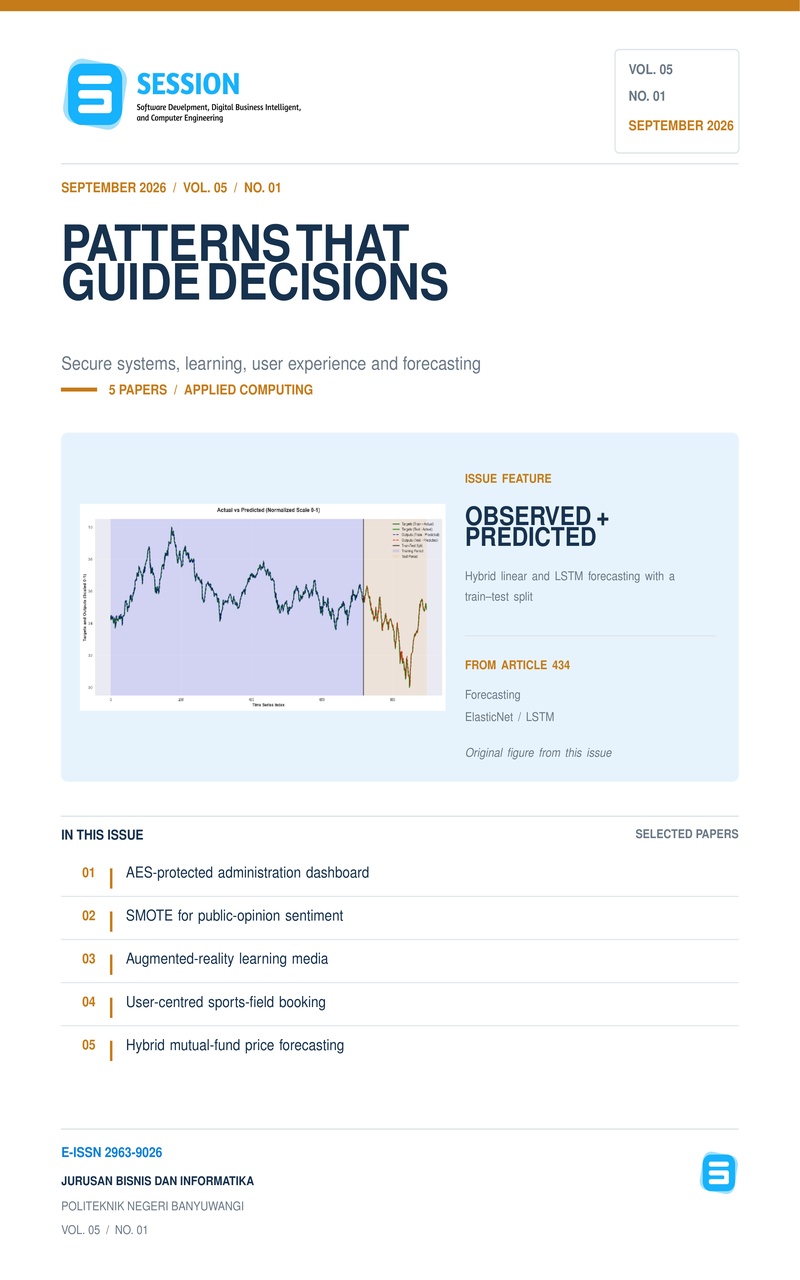
Peramalan Harga Reksa Dana di Indonesia dengan Pendekatan Linear dan Hibrida
DOI:
https://doi.org/10.57203/session.v5i1.2026.28-36Keywords:
ElasticNet, Autokorelasi, LSTM, Model Hibrida, Time Series, Reksa DanaAbstract
Pasca pandemi COVID-19, pasar modal Indonesia menunjukkan dinamika yang kompleks, mendorong peningkatan minat investasi pada instrumen seperti reksa dana. Prediksi harga untuk aset semacam ini secara historis sering mengandalkan model-model yang kompleks, namun efektivitasnya pada data dengan karakteristik autokorelasi yang sangat tinggi masih menjadi pertanyaan. Penelitian ini bertujuan untuk mengevaluasi pendekatan pemodelan yang paling efisien dalam konteks tersebut dengan mengintegrasikan serangkaian faktor fundamental dan teknikal. Menggunakan teknik regresi linear regularisasi (ElasticNet) yang diperkuat dengan fitur lag danPrincipal Component Analysis (PCA), serta model hibrida canggih yang mengombinasikan ElasticNet dengan Long Short-Term Memory (LSTM) untuk memodelkan residual, studi ini mengevaluasi efektivitas dari kedua pendekatan. Hasil menunjukkan bahwa model linear tunggal mampu mencapai akurasi prediksi yang sangat tinggi (R2 > 0.96), yang didominasi oleh kuatnya sinyal autokorelasi. Lebih lanjut, penambahan model LSTM untuk menangkap pola non-linear pada residual terbukti tidak memberikan peningkatan kinerja yang signifikan secara statistik, sebuah temuan yang divalidasi oleh Uji Diebold-Mariano. Dengan demikian, studi ini menyoroti pentingnya pemilihan model yang sesuai dengan karakteristik data, di mana untuk peramalan time-series dengan persistensi tinggi, pendekatan linear yang lebih sederhana dan dapat diinterpretasikan terbukti lebih efisien dan praktis.
References
[1] S. M. Rizky, B. Andini, M. Hasda, M. Syaipudin and W. F. R. Sudirman, "Development of Mutual Funds in The Indonesian Capital Market," Journal of Financial and Business, vol. 1, no. 1, pp. 11-22, Jul 2024.
[2] L. H. Ningrum, T. Marwa, I. Asngari and S. Andaiyani, "Evaluating the Impact of Inflation and Exchange Rates on the Net Active Value (NAV) of Conventional Mutual Funds in Indonesia," 2024.
[3] D. A. Navastara, F. R. A. Hidiya and A. Y. Wijaya, "Prediction of Indonesian Stock Price Using Combination of CNN and BiLSTM Model," in International Conference on Information Technology and Computing 2023, ICITCOM 2023, Yogyakarta, 2023.
[4] C. Mingard, H. Rees, G. Valle-Pérez and A. A. Louis, "Deep neural networks have an inbuilt Occam’s razor," Nature Communications, vol. 16, no. 1, Dec 2025.
[5] N. P. Mariyani, P. W. Saitri and N. P. Y. Mendra, "Predicting Stock Returns in Indonesian Technology Companies," International Journal of Accounting & Finance in Asia Pasific, vol. 8, no. 1, pp. 94-110, Feb 2025.
[6] Z. Makarim and M. Anas, "The Effect of Macroeconomics and JSEC on mutual fund NAV During the Pandemic," in International Student Conference on Business, Education, Economics, Accounting, and Management (ISC-BEAM), 2024.
[7] P. K. D. Lubis, C. L. N. Manalu, A. A. Lubis, L. M. Tambunan and F. Saputra, "The Role of the Capital Market in Increasing Economic Growth in Indonesia," Indonesian Journal of Interdisciplinary Research in Science and Technology, vol. 2, no. 5, pp. 557-568, May 2024.
[8] V. R. Joseph, "Optimal ratio for data splitting," Stat Anal Data Min, vol. 15, no. 4, pp. 531-538, Aug 2022.
[9] I. Jolliffe, "Principal Component Analysis," in Encyclopedia of Statistics in Behavioral Science, 2005.
[10] R. N. Fahmi, R. S. R. N. E. A. Sarno and A. T. Haryono, "Indonesian Stock Price Prediction Using Random Effect Model with Technical Indicators in Panel Data," in 2024 Beyond Technology Summit on Informatics International Conference, BTS-I2C 2024, Jember, 2024.
[11] M. Diqi, M. E. Hiswati and N. Wijaya, Stacked Gated Recurrent Units and Indonesian Stock Predictions: A New Approach to Financial Forecasting, 2024.
[12] F. X. Diebold and R. S. Mariano, "Comparing Predictive Accuracy," Journal of Business & Economic Statistics, vol. 13, no. 3, pp. 253-263, 1995.
[13] A. Boonprasope and K. Y. Tippayawong, "Predicting Healthcare Mutual Fund Performance Using Deep Learning and Linear Regression," International Journal of Financial Studies, vol. 12, no. 1, Mar 2024.
[14] F. Y. A’la, "Indonesian Sentiment Analysis towards MyPertamina Application Reviews by Utilizing Machine Learning Algorithms," Journal of Informatics Information System Software Engineering and Applications (INISTA), vol. 5, no. 1, pp. 80-91, Nov 2022.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Gymnastiar Al Khoarizmy, Feryadi Yulius, Elok Fiola

This work is licensed under a Creative Commons Attribution 4.0 International License.
Copyright :
Authors who publish their manuscripts in this journal agree to the following conditions.
- The copyright on each article belongs to the author(s).
- The author acknowledges that Jurnal SESSION: Software Development, Digital Business Intelligence, and Computer Engineering has the right to be the first to publish with a Creative Commons Attribution 4.0 International license (Attribution 4.0 International (CC BY 4.0).
- Authors can submit articles separately, arrange for the nonexclusive distribution of manuscripts that have been published in this journal into other versions (e.g., sent to the author's institutional repository, publication into books, etc.), by acknowledging that the manuscript has been published for the first time in the Jurnal SESSION: Software Development, Digital Business Intelligence, and Computer Engineering.
License:

Jurnal SESSION: Software Development, Digital Business Intelligence, and Computer Engineering is licensed under a Creative Commons Attribution 4.0 International License.
This license permits anyone to copy and redistribute this material in any form or format, compose, modify, and make derivatives of this material for any purpose, including commercial purposes, as long as the author credits the original work.